
From Data Centers to Your Wallet: What SK Hynix’s Record Q3 Means for the Future of Everyday Tech
If you have noticed that the newest laptops, smartphones, and AI-powered servers carry a heavier price tag than just a year ago, a single earnings report from SK Hynix may explain why. The South Korean memory chipmaker just delivered a Q3 that smashed every record in its history — and the ripple effects will reach everything from cloud subscription pricing to the release schedules of next-generation devices. As the world’s leading supplier of high-bandwidth memory feeding AI infrastructure, SK Hynix’s performance this quarter is far more than a corporate milestone; it signals how tightly memory supply will shape the broader technology economy in the years ahead.
Artist’s rendering of the SK Hynix Cheongju Campus P&T7.
The Financial Headlines: A Quarter Without Precedent
SK Hynix reported third-quarter revenue of 104.62 trillion won (~$78 billion), surpassing 100 trillion won (~$75 billion) for the first time in the company’s history. Operating profit hit an all-time high of 83.33 trillion won ($62 billion), with an extraordinary operating margin of 80%. Net profit reached 39.78 trillion won ($30 billion), while the company’s net cash position swelled to 98.7 trillion won (~$74 billion).
MS Hwang, research director at Counterpoint Research, emphasized the weight of these numbers: “SK Hynix’s third-quarter results are very significant in terms of hitting record-high earnings and delivering on shareholder value,” he noted, adding that the results exceeded even optimistic forecasts: “First and foremost, operating profit beat expectations again, coming in at 83 trillion won [~$62 billion] versus the consensus of 77 trillion won [~$57 billion].”
Why DRAM Prices Leapt Past $2/Gb
The engine behind this record quarter was a dramatic shift in memory pricing. Counterpoint Research tracked standard DRAM prices climbing from 20 cents to 30 cents per Gb, then surging all the way to $2 per Gb — a move that expanded the global DRAM market to $200 billion. “The driving force behind this is rising prices,” Hwang said. “Prices that used to sit around 20 to 30 cents per Gb have now soared to $2.”
Looking further ahead, Hwang projects that HBM4 — the most advanced generation of high-bandwidth memory — will see unit prices jump even higher to $4 per Gb. For everyday tech users, this is not just a supplier story; it directly influences the cost of every AI training cluster, data-center upgrade, and premium consumer device that depends on cutting-edge memory.
HBM4 Myths and Missteps: False Alarms Cleared
Earlier market speculation had clouded the picture. “Over the past few months, the market has been plagued by two major misconceptions and concerns regarding HBM: That SK was facing technical hurdles in supplying HBM4 to Nvidia, and that HBM adoption volumes per chip might decrease,” Hwang explained. He confirmed that as of October, both concerns have proven to be fake alarms or have been largely resolved.
Nvidia, the chipmaker at the center of the AI hardware race, has cleared early HBM4 bottlenecks, removing one of the biggest uncertainties for the entire supply chain.
A Structural Shortage That Could Last Through 2030
With AI expanding into enterprise computing, robotics, and autonomous vehicles, SK Hynix expects the memory shortage to be structural, continuing through 2030. The company points to the manufacturing complexity of 10 nm-class, sixth-generation DRAM and 321-layer NAND as a key factor limiting how quickly new capacity can come online.
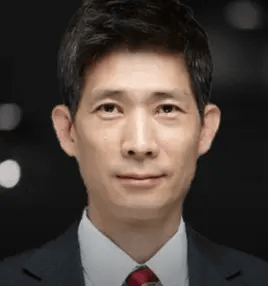 MS Hwang (Source: Counterpoint Research)
To lock in revenue against this prolonged tightness, SK Hynix reported signed long-term agreements (LTAs) with 14 tech giants, covering over 50% of capacity for 2027 to 2028. Hwang pointed out that infrastructure now absorbs more than half of the sector’s capital spending: “Today, more than half of the memory industry’s capital expenditure goes into infrastructure,” he said. He added, “This shift in corporate governance leading to stricter capital discipline could ultimately rewrite the traditional memory business cycle.”
Solidigm IPO Off the Table — But Massive Investment Still in Play
In a notable strategic shift, SK Hynix announced it had discontinued its review of a potential U.S. IPO for Solidigm, its flash memory and solid-state drive subsidiary. CEO Kwak Noh Jung explained the rationale: “The IPO was intended to raise external capital for the expansion of Solidigm’s production facilities,” but added, “However, after carefully considering recent financial market conditions and other factors, we concluded that proceeding at this time would not be the best way to achieve the originally anticipated outcome. We have therefore discontinued our review.”
Hwang noted the broader investor implications: “The Solidigm IPO raised issues around a dual listing… If the returns aren’t flowing back to shareholders, it’s very difficult to re-rate the stock.”
Meanwhile, SK Hynix announced an expanded fiscal year 2026 shareholder return program of 100 trillion won (~$75 billion), including cash dividends over 30 trillion won (~$22 billion) and buybacks exceeding 60 trillion won (~$45 billion), supported by Kioxia investment gains.
According to a Bloomberg report citing people familiar with the negotiations, Solidigm is in talks with the U.S. Commerce Department to invest $45 billion in a new U.S. chip plant. Before committing to what would be the first new major flash-memory chip production facility on American soil, Solidigm is seeking U.S. government permission to send equipment to upgrade an existing plant in Dalian, China.
Two Looming Risks: Cloud Spending Pullback and Samsung’s HBM4 Surge
No earnings story is complete without its caveats. Counterpoint Research flagged the risk of reduced cloud spending. Hwang warned of a possible repeat of 2018: “The single most severe threat would be a scenario reminiscent of 2018, where cloud service providers simultaneously pull back on their order volume,” he cautioned. He also highlighted intensifying competition: “We anticipate that Samsung will surpass SK Hynix from the HBM4 generation, leading the market share in 2027.”
SK Hynix management responded that it expects to preserve its market lead through proprietary packaging and customer partnerships.
Common Misconceptions About This Earnings Story
- “Record profits mean chip prices will drop for consumers soon.” In reality, the company itself projects a structural shortage through 2030, meaning supply will remain constrained even as earnings soar.
- “SK Hynix is losing its edge because of HBM4 delays.” Counterpoint Research confirmed that alleged technical hurdles were among the “two major misconceptions and concerns” that had “plagued” the market — both largely resolved as of October.
- “The canceled Solidigm IPO signals financial distress.” CEO Kwak Noh Jung framed the decision as a strategic choice based on market conditions, not liquidity problems — the company holds 98.7 trillion won (~$74 billion) in net cash.
- “Long-term agreements protect buyers, not sellers.” The LTAs with 14 tech giants actually lock in revenue for SK Hynix, covering over 50% of capacity for 2027 to 2028, reducing downside risk for the supplier.
Quick-Reference Checklist for Tech Readers
- Revenue milestone: SK Hynix crossed 100 trillion won (~$75 billion) in quarterly revenue for the first time.
- Profit margin: An 80% operating margin is exceptional for a hardware manufacturer and well above typical semiconductor industry averages.
- Price surge: Standard DRAM went from 20 cents to $2 per Gb; HBM4 is projected to reach $4 per Gb.
- Supply outlook: Shortage expected to persist through 2030 due to complexity of 10 nm-class, sixth-generation DRAM and 321-layer NAND production.
- Competitive watch: Samsung is expected to surpass SK Hynix from the HBM4 generation by 2027.
- Shareholder action: 100 trillion won (~$75 billion) in returns announced for fiscal year 2026.
- Investment pipeline: Solidigm is pursuing a $45 billion U.S. chip plant via talks with the U.S. Commerce Department, while seeking approval for equipment upgrades at its Dalian, China facility.
Frequently Asked Questions
What does a structural memory shortage mean for everyday consumers?
When SK Hynix and its peers cannot produce enough DRAM and NAND to meet demand, component costs rise throughout the electronics supply chain. This affects pricing for devices that depend on high-bandwidth memory and large-capacity storage — from AI systems powering cloud services to products enabling robotics and autonomous vehicles. The shortage is expected to continue through 2030, so these pressures are unlikely to ease quickly.
Why did SK Hynix cancel the Solidigm IPO?
CEO Kwak Noh Jung stated the listing was originally meant to raise external capital for Solidigm’s production facility expansion. However, after evaluating “recent financial market conditions and other factors,” the company concluded that proceeding was not the best path to the anticipated outcome. Hwang of Counterpoint Research added that the proposed dual listing raised governance concerns — if shareholder returns are diluted, “it’s very difficult to re-rate the stock.”
Is Samsung really a serious threat in HBM4?
Hwang’s analysis suggests yes: “We anticipate that Samsung will surpass SK Hynix from the HBM4 generation, leading the market share in 2027.” However, SK Hynix management maintains that proprietary packaging technology and deep customer partnerships will help preserve its lead.
How could a cloud spending pullback affect the market?
Hwang warned of a scenario “reminiscent of 2018” where cloud service providers simultaneously pull back on their order volume. If major buyers cut spending in unison, the pricing power that drove SK Hynix’s record margins could erode rapidly, potentially triggering a broader downturn across the memory sector.
What is the role of long-term agreements in this story?
The LTAs signed with 14 tech giants cover over 50% of capacity for 2027 to 2028. According to Hwang, “Today, more than half of the memory industry’s capital expenditure goes into infrastructure,” and this governance shift “could ultimately rewrite the traditional memory business cycle.” These agreements reduce uncertainty for the supplier while locking in supply for major tech companies.
Action Advice: What to Watch and Do Next
For readers navigating the tech landscape on MyTechDailyNews, here are concrete steps to stay ahead of the curve:
- Plan tech purchases with memory availability in mind. If your upcoming upgrade or deployment depends heavily on memory capacity, evaluate whether timing matters given the projected shortage through 2030.
- Track Samsung’s HBM4 milestones. If Samsung delivers on the forecast to surpass SK Hynix from the HBM4 generation by 2027, the resulting competition could shift the pricing landscape — a potential signal for timing future hardware decisions.
- Monitor long-term agreement news. Additional LTAs or renegotiations involving SK Hynix and the 14 tech giants can alter the supply-demand balance and influence downstream component availability.
- Follow U.S. chip manufacturing developments. The $45 billion Solidigm plant discussions with the U.S. Commerce Department and equipment approval for the Dalian, China upgrade are part of a larger reshoring narrative shaping where and how chips get made.
- Keep an eye on cloud spending data. Quarterly reports from major cloud service providers are early indicators of whether the 2018-style pullback risk materializes and pressures the memory market.
The Bigger Picture: A Memory Cycle Being Rewritten
What SK Hynix’s Q3 ultimately signals is that the decades-old rhythm of the memory industry may be fundamentally changing. As Hwang observed, stricter capital discipline and governance shifts “could ultimately rewrite the traditional memory business cycle.” For tech consumers, enterprise buyers, and industry watchers alike, understanding this transformation is central to anticipating how much the devices, services, and infrastructure of tomorrow will cost and when they will actually become available. The numbers in this single earnings report are, in effect, leading indicators for the next phase of the AI-powered technology era — a phase that MyTechDailyNews will continue to track closely for you.