
Intel Moves on 18A Production and 14A Tape-Out Plans While Lip-Bu Tan Flags Possible AMD Cooperation
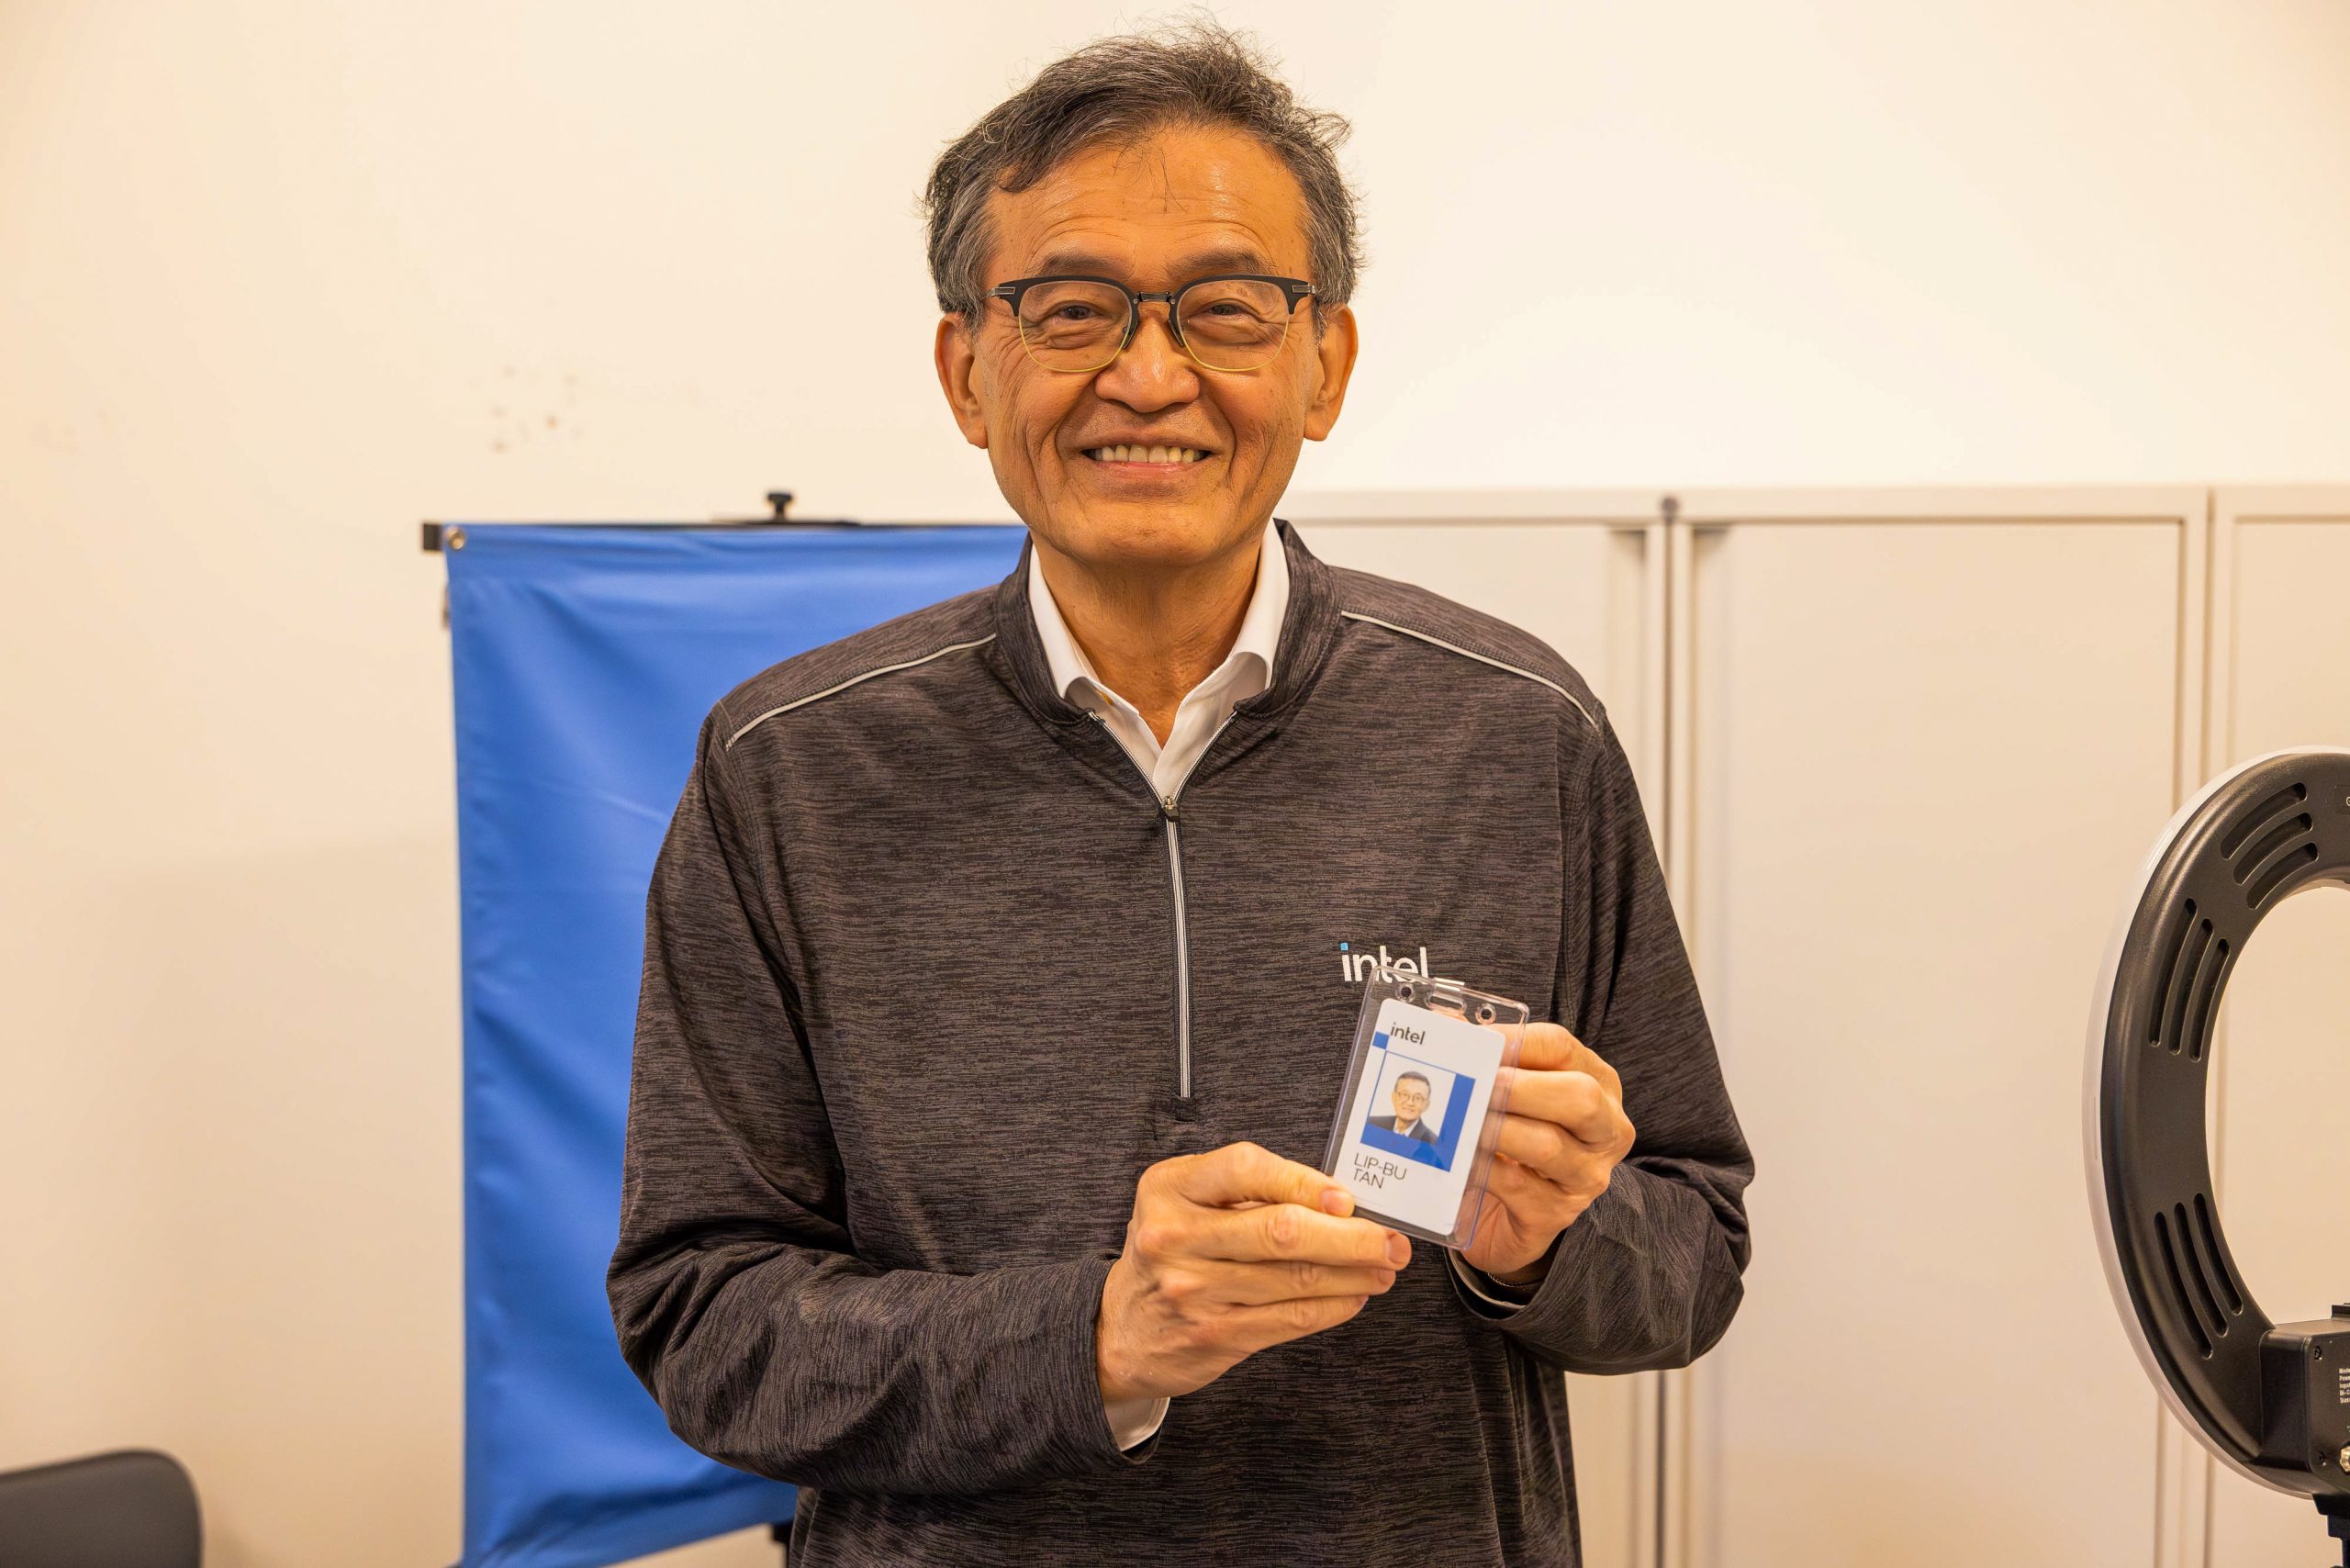
Recently, at a fireside talk hosted by the Chinese-American Semiconductor Professionals Association, CASPA, on October 24, Intel CEO Lip-Bu Tan framed the company's next phase around three public priorities: keep pushing advanced process development, win customer confidence through direct problem solving, and compete for CPU performance leadership while exploring whether cooperation with AMD is possible. The discussion made clear that Intel's manufacturing story is not only about one factory or one chip generation; it involves process readiness, foundry customer trust, packaging supply quality and the competitive boundary between suppliers.
What Lip-Bu Tan Said at a Glance
- 18A status: Tan said Intel's 18A process has entered production. This gives the company a concrete milestone to point to while it rebuilds its position in advanced manufacturing.
- 14A timing: Intel already has a 0.5 version PDK for 14A, will release a 0.9 version PDK soon and plans a 1.0 version PDK early next year to support formal mass production.
- Competitive posture: Tan said Intel will compete for CPU performance leadership, but he also left room for the unexpected by saying he has discussed possible cooperation areas with AMD.
- AMD conversation: Tan said he has talked with AMD Chairman and CEO Lisa Su about future areas of possible cooperation, without naming a specific project.
- Customer process: Tan highlighted a customer case in which a client waited six to eight months for a meeting, then raised 15 issues, and Intel gained deeper cooperation by addressing them item by item.
- Channel view: KeyBanc's recent survey pointed to Intel foundry orders involving Broadcom and Google, plus reported interest or arrangements involving Microsoft and Nvidia, while also describing evaluation work by Amazon, Anthropic and SpaceX/Tesla Terafab.
- Packaging quality: The same channel report described substrate yield challenges tied to EMIB-T advanced packaging, with figures of 50% to 60% overall and a split between suppliers.
18A Production and 14A: Two Nodes, Two Different Questions
For 18A, the public update is about status. Tan said the process is in production, which moves the discussion from roadmap promises to delivery. For 14A, the update is less about a finished product and more about the set of design tools customers need before they can seriously commit to a node. That is why the PDK schedule matters: a process may look promising on paper, but designers need validated rules, models and documentation to turn a roadmap into a chip program.
The PDK Ladder: 0.5, 0.9 and 1.0 Versions
According to Tan, Intel currently has a 0.5 version PDK for 14A. He said a 0.9 version PDK will follow soon, and a 1.0 version PDK is planned for early next year to support formal mass production. In foundry language, a PDK is the set of design rules, models and technical files a wafer maker provides to chip design companies.
| 14A PDK stage | Practical meaning in the industry | Status described by Intel |
|---|---|---|
| 0.5 version | An early-test stage, useful for initial feasibility work and early engagement. | Already available. |
| 0.9 version | A more mature stage that indicates the process node is moving toward tape-out capability and risk production, a key step before mass production. | Planned soon. |
| 1.0 version | A production-oriented stage, intended to support formal mass production. | Planned for early next year. |
This version sequence helps separate three ideas that are often mixed together: early availability, ability to tape out and readiness for volume production. A node can be "here" in one sense but not yet ready in another.
Why "Lecturing" Customers Became Part of the Story
The most human detail in the talk was Tan's account of customer trust. He said one customer waited six to eight months to meet him after he became Intel CEO. During the meeting, that customer listed 15 problems from Intel's past. Tan acknowledged that, in the past, some company management could be tempted to talk at customers rather than listen, even lecturing them. He said he addressed the list item by item and resolved the issues, and the customer later chose to deepen cooperation with Intel.
For a General audience, this part matters because it reframes what a foundry business actually sells. It is not only wafer capacity or a node name. It is also responsiveness, predictability and the willingness to treat a customer's complaint list as a work order rather than a public-relations problem.
AMD Cooperation: A Remarkable Public Signal, Not Yet a Plan
Tan said he has spoken with AMD Chairman and CEO Lisa Su about areas where the two companies could potentially cooperate in the future. The statement did not identify a deal, a product, a facility or a timeline. Even so, it is significant because AMD and Intel have long been viewed through the lens of competition, especially in CPUs. If the conversation moves beyond a fireside remark, it could change how the industry thinks about supplier relationships, especially in a foundry market where capacity, packaging and process leadership are scarce resources.
For now, the safest reading is simple: Intel is not treating every competitive relationship as a closed door, but it has not announced a specific collaboration either.
What KeyBanc's Channel Survey Adds
KeyBanc's recent channel survey provides a view from outside the company, and it should be read as reporting rather than as confirmed corporate agreements. The survey said Intel has secured multiple foundry orders, including producing network switch chips for Broadcom and server CPUs for Google. The report also mentioned that Microsoft server processors and Nvidia gaming GPUs are reported to be foundry-manufactured by Intel.
The channel note also highlighted that several other major technology companies remain in an evaluation phase. Amazon, Anthropic and SpaceX/Tesla Terafab are described as customers assessing Intel's 18A-P and 14A process technologies, with many showing a preference for 14A. This detail is useful because it suggests that customers are not all converging on the same answer; they are weighing different nodes, schedules and packaging needs.
The most eye-catching claim in the report concerned Apple. KeyBanc suggested that Apple has reached a long-term foundry agreement with Intel covering multiple product generations, involving M-series and A-series chip production and using 14A rather than the previously discussed 18A-P process. That report has not been confirmed by Apple or Intel, and it remains subject to market debate.
Advanced Packaging: The Substrate Yield Detail
Beyond front-end wafer nodes, packaging has emerged as another area where execution quality can influence customer decisions. According to the KeyBanc report, the production yield for substrates used with Intel's EMIB-T advanced packaging technology is currently about 50% to 60%. The report said the main supplier Ibiden is performing better, while another supplier, UMTC, has yield around 20% to 30%.
This kind of supply-chain detail may sound technical, but its consumer-facing implication is straightforward: advanced chips are not only designed; they are packaged, integrated and delivered at scale. If substrate supply is uneven, customers may evaluate timelines, reliability and alternative options more closely.
How Readers Can Make Sense of the Story
For everyday tech readers, the value of this update is not to predict a single winner. It is to understand the moving parts behind the chips in servers, networking devices, PCs and future AI infrastructure. Intel's 18A production milestone, the 14A PDK roadmap, the customer-trust narrative, the KeyBanc channel view and the possible AMD cooperation thread all point to a broader question: can Intel convert process progress into reliable, large-scale manufacturing value fast enough to influence the market?
Common Misconceptions
- Misconception: A 0.9 version PDK means mass production has started. The explanation in the talk describes 0.9 as a stage that points toward tape-out capability and risk production. The 1.0 version PDK is the one tied to formal mass production.
- Misconception: The Apple deal is official because a channel report said so. The report attributed the Apple-Intel agreement to KeyBanc's view, and the article noted that neither Apple nor Intel has confirmed it.
- Misconception: Intel and AMD have announced a partnership. Tan said he has discussed potential cooperation with Lisa Su, but no specific collaboration was disclosed.
- Misconception: All foundry customers prefer the same process. The channel information said some customers are evaluating both 18A-P and 14A, and many lean toward 14A.
- Misconception: Node progress automatically solves packaging and supply problems. The same reporting described substrate yield issues, showing that advanced packaging and component supply can remain separate challenges.
FAQ
What is the latest status of Intel's 18A process?
Lip-Bu Tan said Intel's 18A process has entered production. That is the clearest status update from the October 24 discussion.
What progress did Intel report for 14A?
Intel currently has a 0.5 version PDK for 14A. A 0.9 version PDK is planned soon, and a 1.0 version PDK is scheduled for early next year to support formal mass production.
What is a PDK?
A PDK is a set of design rules, models and technical documents used by chip designers to work with a foundry process. Version numbers help indicate whether a process is early-test, tape-out ready or production ready.
Did Intel CEO Lip-Bu Tan talk about AMD?
Yes. He said he has communicated with AMD Chairman and CEO Lisa Su about possible future cooperation areas, though he did not provide specific directions.
What does the 15-issue customer story show?
It shows that Intel's CEO discussed customer trust as an active repair process. A client waited six to eight months, listed 15 problems, and Intel responded by addressing them item by item, leading to deeper cooperation.
Which customers did KeyBanc associate with Intel foundry work?
KeyBanc's channel report mentioned Broadcom network switch chips and Google server CPUs. It also reported that Microsoft server processors and Nvidia gaming GPUs would be manufactured through Intel foundry work, while noting ongoing evaluations by Amazon, Anthropic and SpaceX/Tesla Terafab.
Is Apple using Intel 14A?
KeyBanc said Apple has reached a long-term agreement covering M-series and A-series chips with 14A planned, rather than 18A-P. The article noted that this has not been confirmed by Apple or Intel.
Why are packaging yields important?
They affect the ability to deliver advanced chip assemblies at scale. KeyBanc said substrates for EMIB-T advanced packaging have about 50% to 60% yield, with Ibiden better and UMTC around 20% to 30%.
Action Suggestions
- Separate milestone language from commercial confirmation. A node entering production, a PDK release or a customer evaluation are different things; treat them separately when summarizing Intel's progress.
- Watch the 14A PDK sequence. The next practical check point is the 0.9 version PDK, followed by the 1.0 version PDK in early next year.
- Track whether AMD cooperation becomes specific. Until a concrete collaboration is named, the discussion with Lisa Su should remain in the "possible" category.
- Read channel reports as signals, not signed contracts. KeyBanc's survey is useful, but Apple-related claims and reported Microsoft/Nvidia arrangements still need official confirmation.
- Pay attention to packaging and substrate supply. If 14A moves toward mass production, yield and supplier performance may influence how smoothly customers can adopt it.
Bottom Line
Intel's public update is less about one big announcement and more about a set of connected signals. 18A is in production. 14A is moving through a staged PDK path. Customer trust is being discussed in concrete terms, including a 15-item problem list and a six-to-eight-month wait that eventually turned into deeper cooperation. The company is competing for CPU performance leadership, but Lip-Bu Tan also opened the door to a conversation with Lisa Su about possible cooperation with AMD. At the same time, KeyBanc's recent channel view suggests Intel is attracting foundry interest while also revealing unresolved questions around 18A-P, 14A adoption and advanced packaging supply.
The next chapter depends less on slogans and more on whether 0.9 becomes available, whether 1.0 arrives early next year as planned, whether more customers choose 14A, and whether reported relationships with Broadcom, Google, Microsoft, Nvidia or even Apple move from channel commentary to officially confirmed business.